Alginate
Films · coatings · bioplastics · cosmetics · pharma
INVESTOR PRESENTATION · 2026
Biotech. Existing markets. Norwegian.
02 / SEANNOVATION
Cultivated seaweed. Customer-specific ingredients. Established markets.
We are a biotech company that buys cultivated seaweed, extracts valuable polymers and tailors them to industrial customers’ specifications.
OUR TARGET INDUSTRIES
03 / SEANNOVATION
How big is the market? As big as the ocean.
of global seaweed is produced in Europe
in goods and services every year (WWF) — and we farm almost none of it
One species · five fractions · a beachhead Europe already pays for: it buys 36% of global alginate demand and relies on Asian imports. Credible, specific, delivery-focused — the first market that funds everything after. SEAnnovation is the missing downstream capacity.
04 / SEANNOVATION
A regenerative, minimal-chemistry biorefinery for Europe.
We turn cultivated seaweed into refined, customer-specific ingredients — the bridge between farmers and industrial buyers.
05 / SEANNOVATION
Part 1 of 2 · We operate in Stages 5–6 and catalyse the full chain.
Without market demand, cultivators cannot scale. Without cultivation volume, downstream customers cannot commit. SEAnnovation unlocks the whole value chain.
06 / SEANNOVATION
Part 2 of 2 · Low volume and high prices currently hold the value chain back.
TODAY
Volume and price hold each other downContracted offtake and in-house processing give farmers certainty to scale production.
Cellulose and co-products absorb cost, so growth does not only depend on premium alginate pricing.
Exact-spec alginate opens industrial buyers who purchase at volume.
SEAnnovation catalyses the value chain: offtake gives farmers certainty, multi-product economics absorb cost, and spec-defined demand brings industrial buyers.
07 / SEANNOVATION
Alginate, cellulose, fucoidan and AlgiCel — functional ingredients that do the work in the customer’s product and process.
Films · coatings · bioplastics · cosmetics · pharma
Barrier layers · composites · membranes
Nutraceutical · cosmetic · bioactive applications
Alginate–cellulose blend · first sale May 2025
Primary feedstocks: Saccharina latissima (sugar kelp) and Alaria esculenta (winged kelp). The financial model uses sugar-kelp assumptions.
08 / SEANNOVATION
COMMERCIAL TRACTION
Only verified relationship stages are shown. Cold prospects are excluded until first contact.
09 / SEANNOVATION
Our business does not depend on these rules — when they take effect, regenerative ingredients become the market standard.
Mandates bio-based and recyclable packaging materials.
Forces Scope 3 disclosure — we deliver audit-ready LCA/EPD data.
Makes Asian alginate imports progressively more expensive.
Political will and funding for European seaweed processing.
Direct advantage for ESG-documented Norwegian supply.
When any of these tighten, SEAnnovation's regenerative model becomes the preferred choice — not the alternative.
10 / SEANNOVATION
Norway already has an alginate industry. Ours is cultivated, cleaner, and complete.
Europe’s largest alginate market remains dependent on Asian supply.
11 / SEANNOVATION
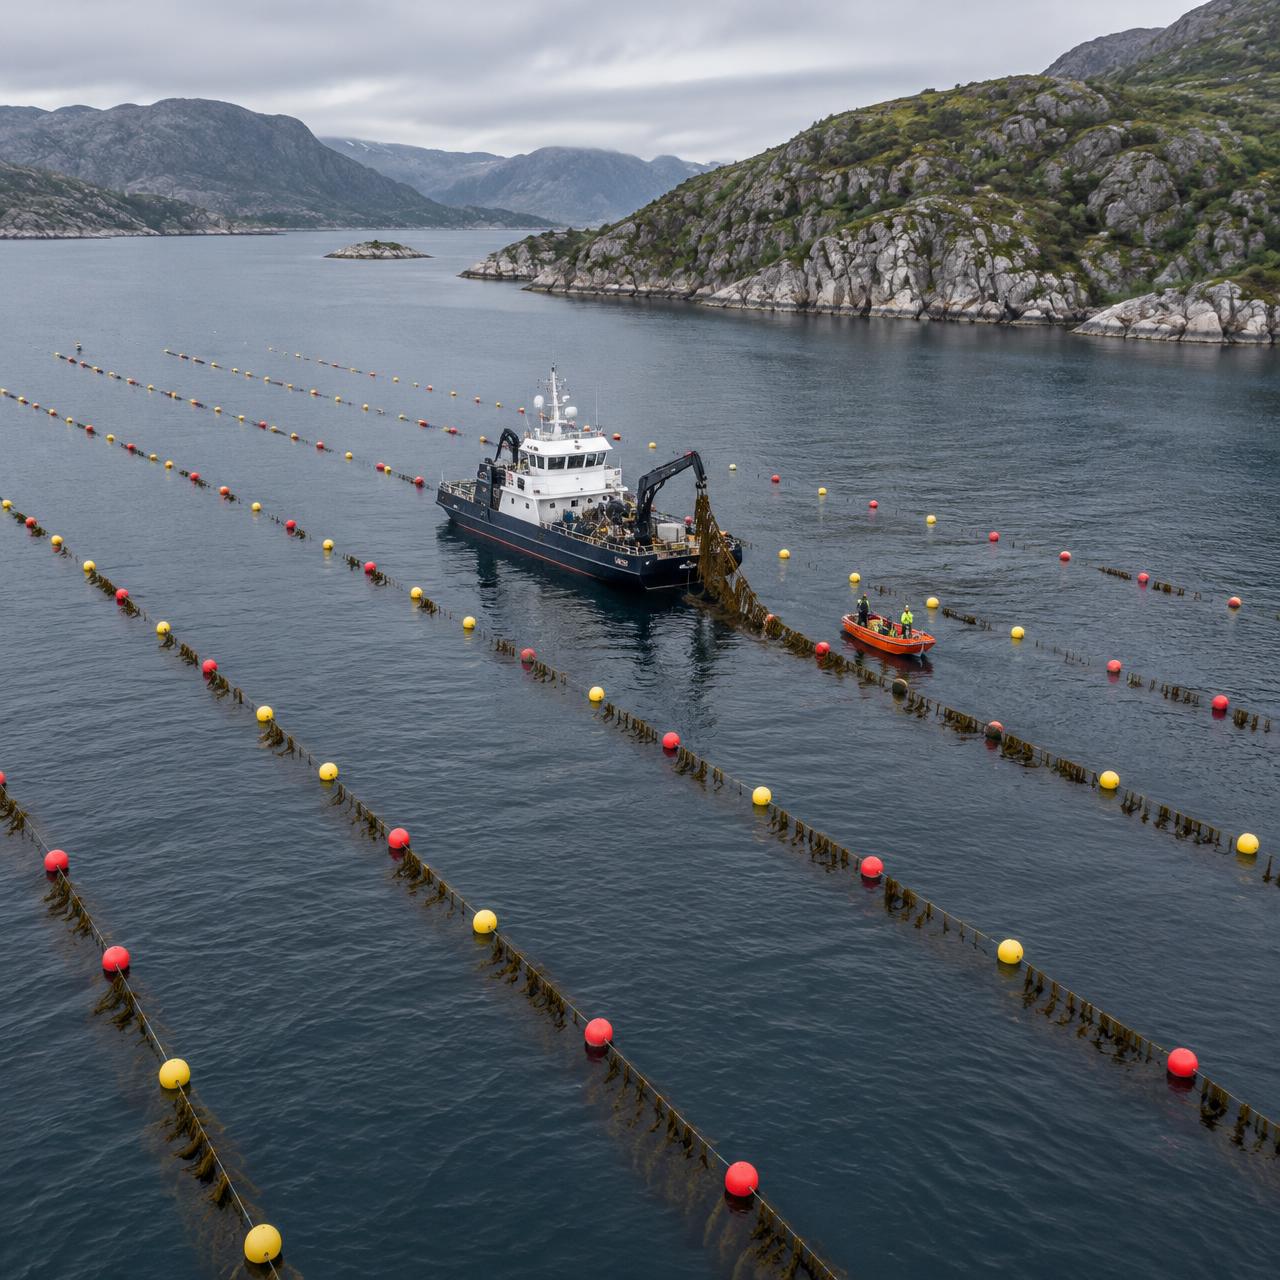
Farmers are waiting for buyers. The investments are made — farmers own the licences and the equipment, ready to scale volumes well beyond today’s harvest.
2027 · BRIDGE SUPPLY
340–460 t2028 · BASE SUPPLY
650 t2029 · EXPANSION
Next waveCapacity is added as customer demand converts.
We do not just buy biomass — we build the demand infrastructure that lets European cultivation scale.
12 / SEANNOVATION
Set production assumptions, choose the team and explore automation.
LIVE OUTPUT · 2028
€0.9MrevenueIndicative shared-process product margins.
EBITDA SENSITIVITY · +10% INPUT · 2028
CAPEX · HUMANOID AUTOMATION
Exploratory option — not a dependency. The base-case P&L works with human-only operations; staged robots can later support repetitive handling.
Production, team and automation choices flow into the P&L on the next slide.
13 / SEANNOVATION
Live output from the production, team and automation choices you set on the operating model slide.
Base inputs reproduce the supplied revenue and variable-cost model. Team choices and illustrative financing are layered on top.
14 / SEANNOVATION
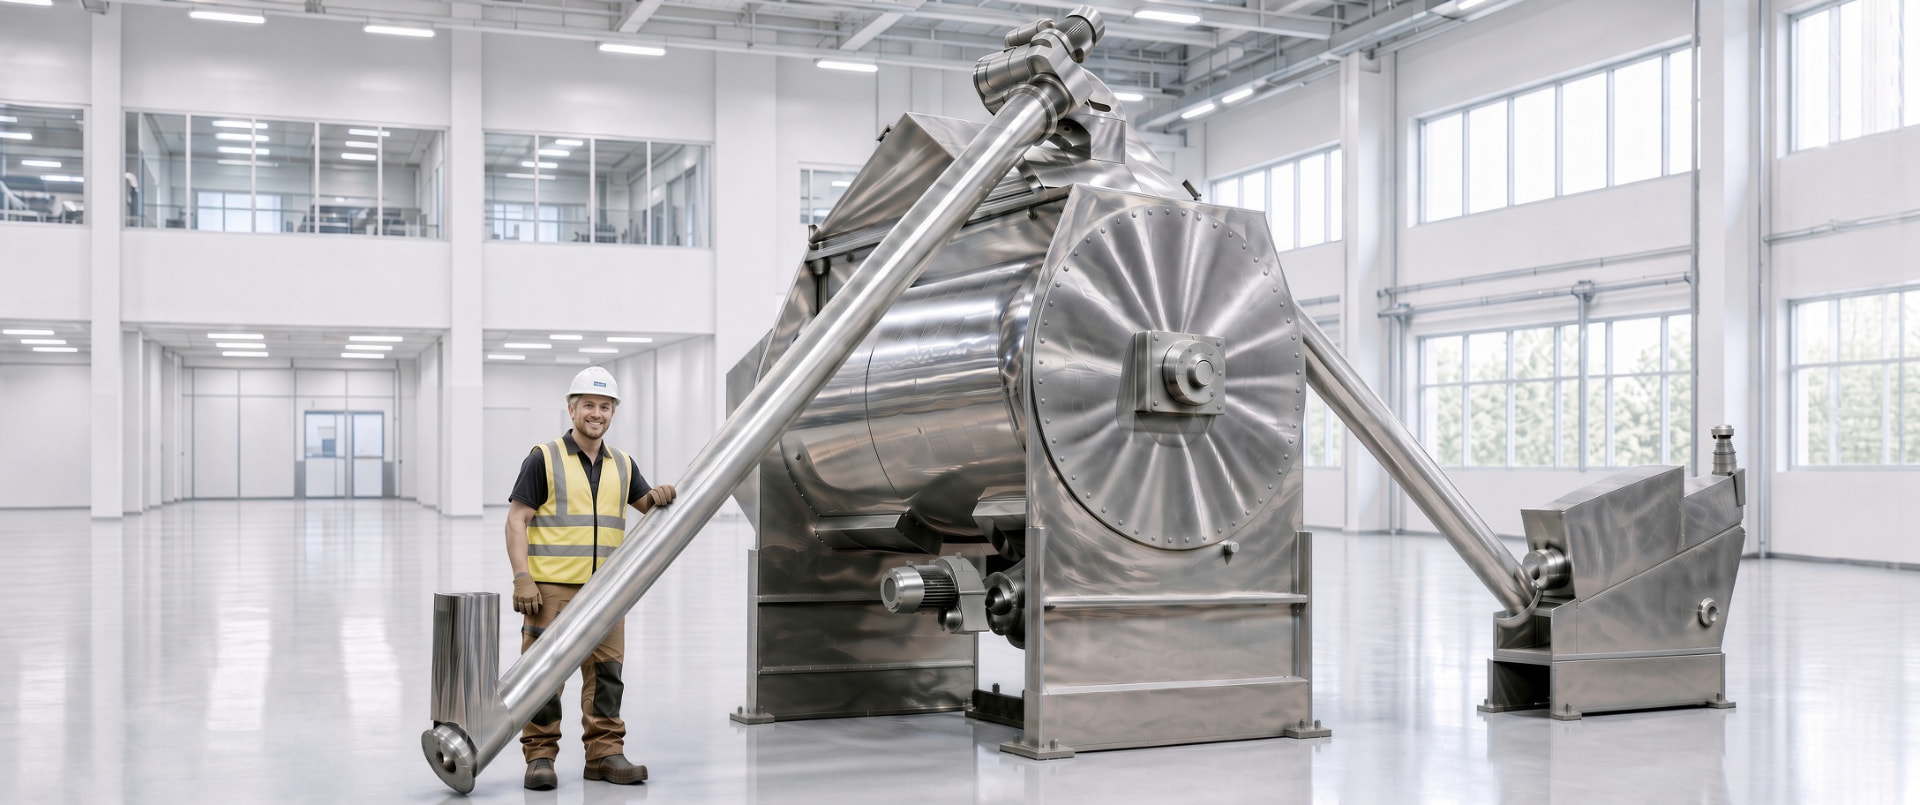
We build ERP, CRM and SCADA ourselves. The systems run as one platform — from customer requirements and recipe to production, quality and traceability.
LIVE TODAY
One operating layer for customers, sales, inventory, production planning, traceability and process recipes.
IN DEVELOPMENT
SCADA-based automation of the complete production line — from raw biomass to repeatable, spec-defined output.
The same system, recipes and process control are reused at every site — so modular biorefineries can be built and run cheaper and more efficiently around the world.
15 / SEANNOVATION
Thorøya offers 14,000 m² of industrial-zoned expansion potential and a deep-water quay — then modular capacity can move closer to cultivation.
2028
1production line1,680 t / year2029
3production lines4,420 t / year2030
4production lines7,935 t / year2030+ · DISTRIBUTED
European modular unitsScaling follows the budget's base case: one line per 2,000 t/year — €0.5M capex per line, depreciated over 8 years, with one production employee per line.
16 / SEANNOVATION
Revenue plus working capital is the base case — the alternatives are ready if conversion or yield slips.
Operations are covered by revenue. A facility finances seasonal kelp purchases — so no new equity is needed while the plan holds.
If yield and offtake stay on track → revenue + working capitalRaise fresh equity to fund operating runway and biomass purchases.
If commercial conversion is slower than planned → equityA smaller equity round plus debt supports a dividend-driven cash-flow profile — without a fixed VC exit horizon.
If ownership horizon matters more than exit speed → patient capitalIllustrative scenario, not a financing offer. Facility availability and terms remain subject to lender assessment.
17 / SEANNOVATION
Founders, operators and specialists building the biorefinery.
Serial entrepreneur, Sunday Power AS exit, Lovable builder and operating-system architect.
LinkedIn ↗
PhD Chemistry, 13+ years in industry and R&D. Former R&D Chief at Jotun; Sunday Power AS exit.
LinkedIn ↗
Four years as Sales Director at Nordic SeaFarm; former H&M Sales Director Spain & Portugal.
LinkedIn ↗
PhD Marine Biotechnology with Nofima heritage and formaldehyde-free process expertise.
LinkedIn ↗
Built Den Stolte Hane to €26M revenue; expert in commercial production scale-up.
LinkedIn ↗
Operations and business development leader driving the Seaspectra platform build.
LinkedIn ↗18 / SEANNOVATION
Grants, committed owners and industry backers have funded every step since 2023.
2023
2024
2025
2026
R&D scale-up
€3.4M secured since 2023 — €1.28M from investors and €2.1M in competitive grants — before Round 4.
19 / SEANNOVATION
From first commercial sales to becoming a European catalyst.
2023–26
2026
2027
2028
2030+
20 / SEANNOVATION
AI-assisted answers grounded in this pitch and the assumptions you have set in the deck.
Beyond alginate — the long-term platform vision and supporting material.
A1 / SEANNOVATION
The processing infrastructure we build for alginate scales to every polymer in the ocean.
Alginate · Iα-cellulose · Fucoidan · Laminarin · Mannitol
Add Alaria · Palmaria · Ulva → phlorotannins · agar · ulvan · peptides · pigments. Each new species opens three new markets.
Pharma & medical device (€500–3 000/kg) · cosmetics marine actives · bio-based materials · food & functional ingredients.
Short-term discipline, long-term ambition. The infrastructure is the moat — species and products scale through it as technology, demand and regulation mature.
A2 / SEANNOVATION
During winter 2026/27 we will be certified to ISO 9001 and ISO 14001 — ready for industrial buyers from the first recurring delivery.
ISO 9001
ISO 14001
Target: both certifications in place during winter 2026/27.
24 / SEANNOVATION
Independent assumptions · original forecast unchanged.
Auto: 2028 1 line · 2029 3 lines · 2030 4 lines — 1 line per 2,000 t, €0.5M capex (8-yr depreciation) and 1 operator (€70k) per line.
Live output
Indicative shared-process product margins.
EBITDA SENSITIVITY · +10% INPUT · 2030
Budget table on the next slide · test scenario only.
25 / SEANNOVATION
Follows the settings on the previous slide.
Test scenario only — the original model and P&L remain unchanged.